An order from an overseas online shop can cost more than its checkout price. Since 1 July 2026, the EU has applied a temporary €3 customs duty to eligible consignments worth up to €150. However, €3 is not necessarily the charge for the whole parcel.
Which purchases are covered?
Article 2 of Regulation (EU) 2026/382 provides for this rate for goods imported under IOSS, the VAT scheme for online sales, or in postal consignments. Other import arrangements may attract normal customs tariffs. Adding €3 automatically to every international parcel would therefore be misleading.
€3 per product or per parcel?
The calculation depends on the goods items in the declaration. Several products can form one item if they share the same classification, description and, where required, origin. The rules and examples appear in section 5.2 of the European Commission guidance.
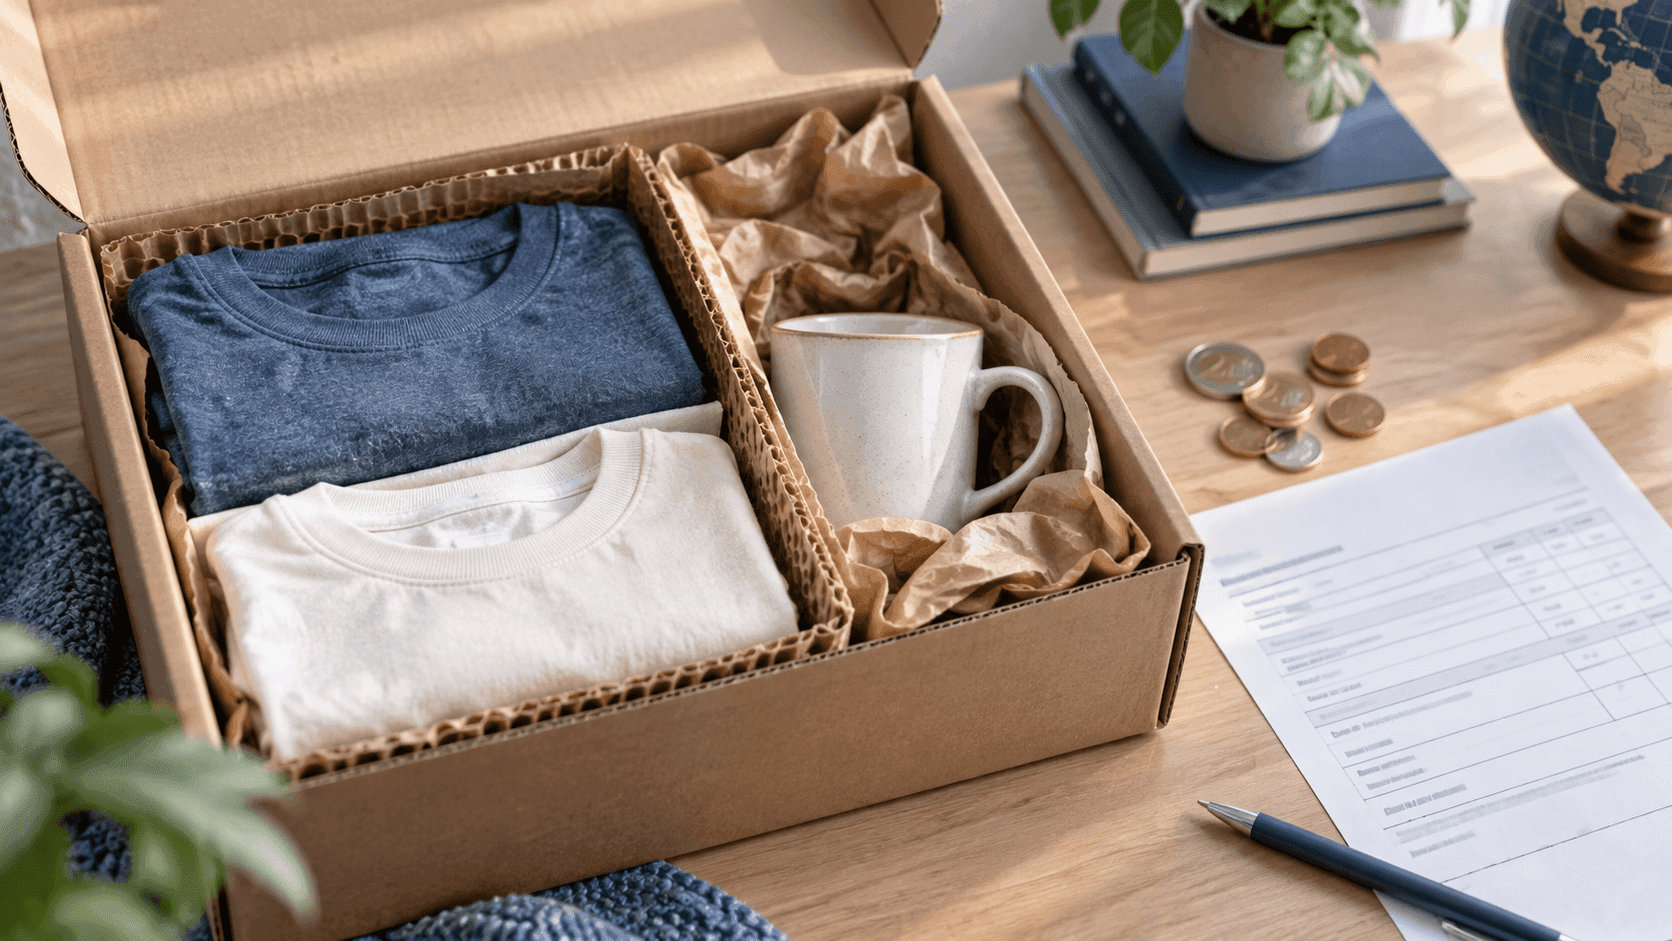
Suppose two identical T-shirts can correctly be declared as one item: the duty is €3. Add a mug as a separate item and it becomes €6. This example assumes the consignment qualifies for the rate; the final calculation depends on a correctly completed declaration.
What else can you be charged?
The duty does not replace VAT, delivery costs or any customs clearance services charged by the carrier. Before buying, ask the seller which charges are included and which may still be payable on import.
What information should you prepare?
Keep the order confirmation, value and quantity of each product. Describe the contents clearly: “two cotton T-shirts and a ceramic mug” is more informative than “personal items”. For an IOSS sale, provide the carrier with the required information using its designated process.
Online sales also involve product identifiers (PID).