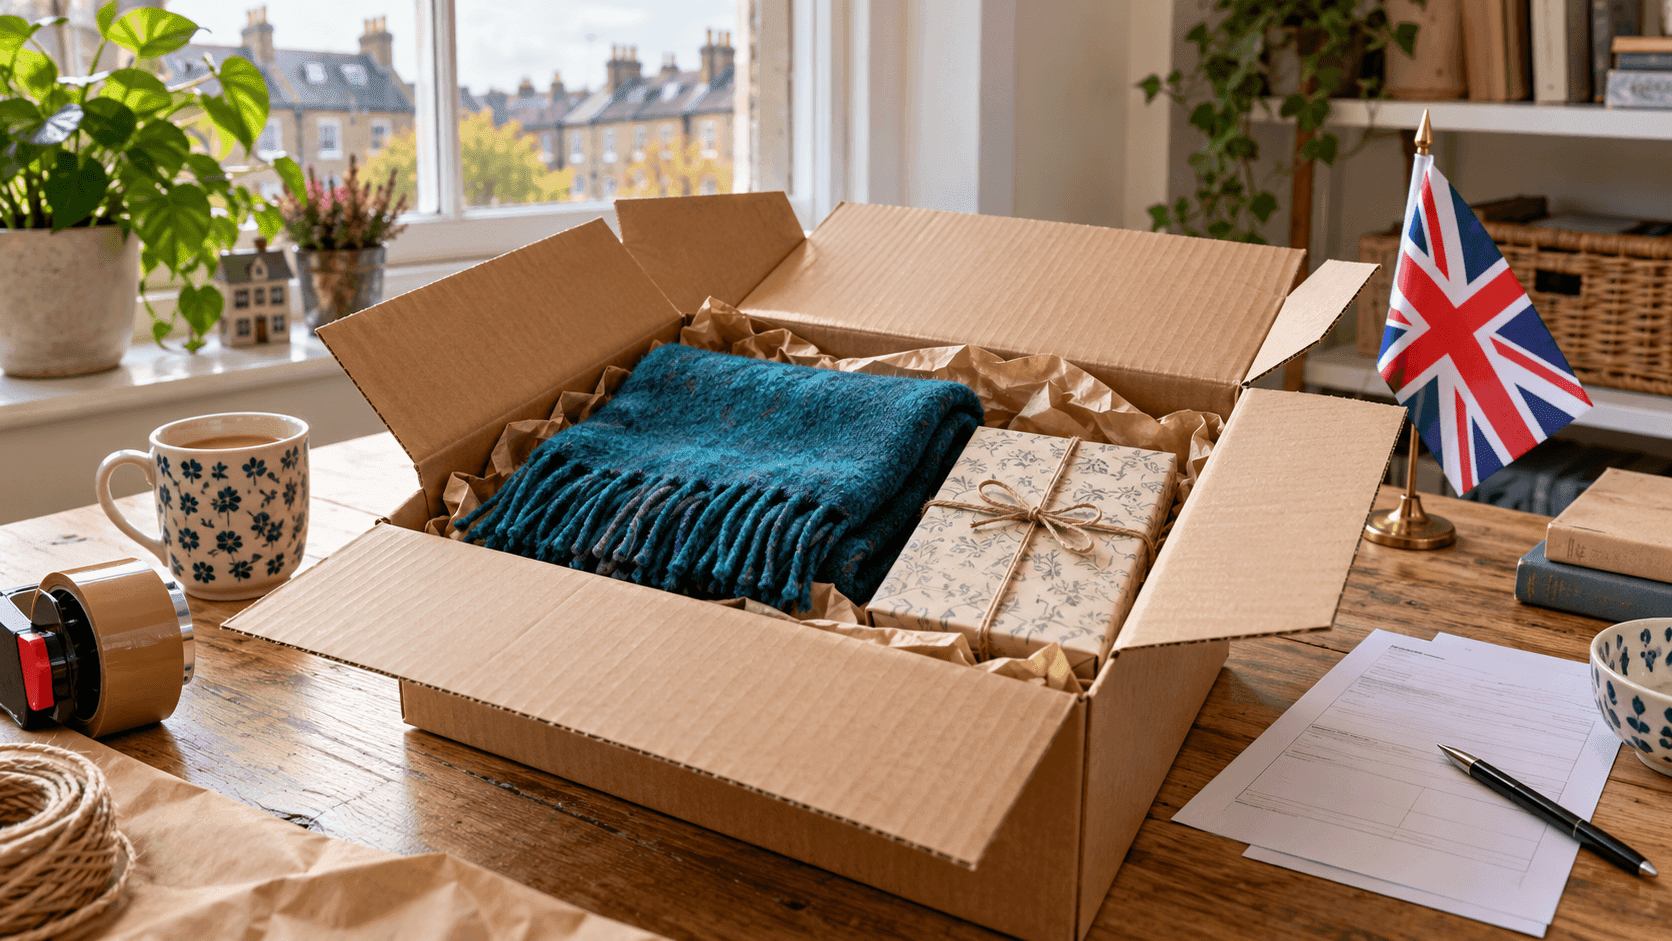
Sending a scarf or book to a relative still involves customs information. Writing “gift” on the box does not explain its contents or value. This guide covers parcels sent from outside the UK to England, Scotland and Wales. Northern Ireland has separate conditions.
When a parcel qualifies as a gift
HMRC treats an occasional shipment from a private individual abroad to a private individual in the UK, for example for a birthday, as a gift when the relevant conditions are met. It must be for personal use and must not have been paid for, directly or indirectly, by anyone in the UK. The declaration must identify it as a gift.
An online purchase delivered directly to the recipient does not qualify for gift relief simply because it marks a special occasion. HMRC explains the conditions and how to declare several gifts packed together.
HMRC: conditions for gift parcels
When the recipient may have to pay
Ordinary non-excise gifts worth £39 or less qualify for import VAT relief. Above £39, import VAT becomes due; above £135, Customs Duty may also apply. The duty rate depends on the goods and their origin. The VAT rate depends on the goods: qualifying books, for example, are zero-rated. Exceeding £39 does not by itself guarantee a positive VAT amount.
Where the carrier collects import VAT, its calculation includes the goods, postage, packaging, insurance and any duty due. The relief threshold and the amount used to calculate tax are therefore different figures. Alcohol, tobacco and some other categories have special conditions; the scarf example does not cover them.
GOV.UK: import VAT and Customs Duty
Information to prepare
List the items, their quantities and individual values. Describe the contents precisely, for example “one wool scarf”, instead of using only “gift”. Keep evidence of value and provide the declaration details through the selected delivery service.
Giving an item away does not make its customs value zero. State its actual value rather than reducing it to a relief threshold. Before packing, confirm that the carrier accepts the items and ask which documents it needs. Personal parcels also need an accurate declaration.
GOV.UK: customs declaration documents
Shipping restrictions: what to check before handing over a parcel